How to Document Household Assets Before an Insurance Claim

To document household assets before an insurance claim, make a room-by-room inventory, photograph your belongings, record identifying details and save purchase evidence. Add current replacement estimates, then store a secure copy that you can access if your home or devices are damaged.
After a burglary, fire or storm, remembering every possession can be difficult. A prepared inventory gives you a record to work from when explaining what you owned. Your policy documents still determine what is covered and how a claim may be settled. RACV’s claims guidance explains the role of ownership evidence and policy documents. RACV
Create a room-by-room inventory
Start with one room and work through the house in a consistent order. Open cupboards, check drawers and include storage areas. RACV recommends working room by room or by category to make the task manageable. RACV
Use a spreadsheet, document or notebook with space for:
- The room or storage location.
- The item description and quantity.
- The brand, model and serial number, where available.
- The purchase date and retailer, if known.
- The original purchase price.
- The estimated replacement cost and date checked.
- References to supporting photographs, receipts or valuations.
Give each entry a simple identifier, such as LIV-001 for the first living room item. Use the same identifier in its photo and receipt filenames so you can connect the records later.
The following checklist can help you work through the property:
| Area | Items to check |
|---|---|
| Living and dining rooms | Furniture, rugs, televisions, audio equipment and games consoles |
| Kitchen and laundry | White goods, small appliances, cookware, crockery and linen |
| Bedrooms | Beds, mattresses, clothing, shoes, bags and jewellery |
| Study | Computers, monitors, printers, office furniture and accessories |
| Garage, shed and storage | Tools, bicycles, sporting equipment and stored belongings |
These are inventory prompts, not a statement that every item is insured. Allianz’s contents guide lists common household categories and notes that exclusions apply. Allianz Australia
You can group ordinary lower-value belongings, such as towels or everyday clothing, for your initial inventory. Record expensive or distinctive items separately. If you do not know an exact purchase date, label it as approximate. Suncorp’s inventory guidance supports recording both individual valuables and categories of everyday possessions. Suncorp
Photographing serial numbers and receipts
Take a wide photograph of each room, followed by closer images of individual items. A room photograph provides context; close-ups capture details that a distant image cannot show.
For appliances, electronics and other identifiable possessions, photograph:
- The whole item.
- Its model and serial-number label.
- Distinctive features and existing wear.
- The receipt or invoice, with purchase details clearly visible.
Suncorp recommends clear photographs, including serial numbers or distinctive markings, alongside images of rooms and storage areas. Suncorp
Type serial numbers into your inventory as well as photographing them. Only photograph labels you can safely reach; check the original packaging or documentation when access is difficult.
Save digital receipts and order confirmations with the relevant entry. For paper receipts, capture the full document and check that the retailer, date, item description and amount are legible.
A consistent filename makes records easier to find. For example, LIV-001-television.jpg and LIV-001-receipt.pdf can both relate to the same inventory entry.
If a receipt is missing, ask your insurer what other evidence it can accept. RACV lists photographs, purchase-related bank or card statements, packaging and valuation certificates among possible forms of ownership evidence. RACV
If your records are destroyed in a disaster, explain this to your insurer. The Insurance Council of Australia states that, for an accepted total-loss claim, ownership evidence or a list of lost property is not required when the evidence was lost or damaged in the insured event. Insurance Council of Australia
Estimating replacement costs
Keep the original purchase price separate from today’s replacement estimate. An appliance bought several years ago may cost a different amount to replace now.
Look up a current item with comparable features and quality. If the original model is discontinued, use a comparable model as a starting point and save the retailer link or screenshot with the date checked.
For example, your inventory might show that a washing machine cost $900 when purchased, while a comparable replacement currently costs $1,200. These illustrative figures describe different things: the historical purchase and the current estimate.
Record estimates in Australian dollars, total each room and then calculate the household total. ASIC’s Moneysmart recommends using today’s replacement prices when assessing your belongings and explains that policies can use replacement value or depreciated value. Moneysmart.gov.au
Compare your total with the contents sum insured shown in your policy schedule. Then check the Product Disclosure Statement (PDS) for limits on particular items or categories. A household total alone does not establish how much you can claim for a valuable watch or jewellery collection.
Allianz notes that higher-value items may need to be specified separately where they exceed the policy’s general limits. The requirements depend on your insurer and policy. Allianz Australia
Useful questions to ask include:
- Does the policy provide replacement cover or depreciated value?
- What limits apply to jewellery, watches or other valuables?
- Do particular items need to be listed separately?
- What evidence or valuation would be needed for an inherited item?
Your replacement estimate helps you prepare and review your cover. It is not a guaranteed settlement amount.
Keeping records securely
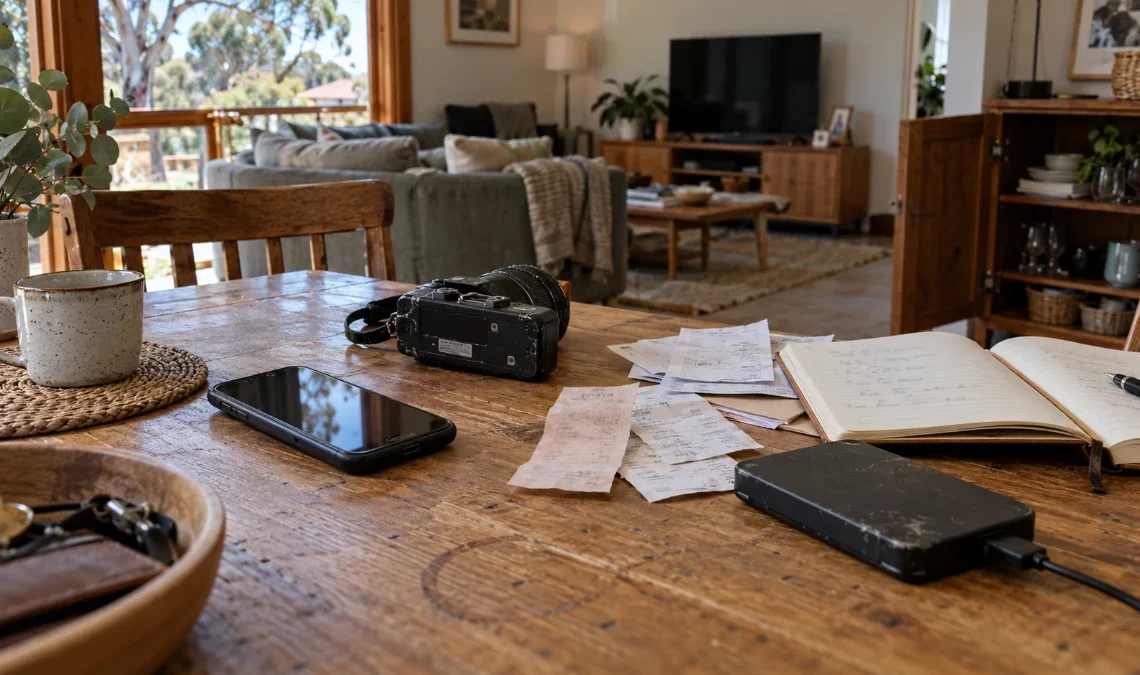
Store your inventory so you can retrieve it even if the phone, computer or paperwork at home is lost. Keep a protected digital copy and a separate backup, with at least one copy accessible from outside the property.
For example, you could keep your working inventory in a private cloud account and an encrypted backup on an external drive stored securely elsewhere. Include the photographs and receipts in the backup, not just the inventory list.
The Australian Signals Directorate’s backup guidance recommends protecting cloud accounts, securing backup devices and testing that files can be restored. Cyber.gov.au
For practical protection:
- Use a strong, unique password or passphrase.
- Enable multi-factor authentication on the cloud account.
- Keep sharing permissions private.
- Disconnect an external backup drive after use.
- Periodically check that you can open and restore the saved files.
Check whether your cloud service provides recoverable backups or simply synchronises files. The ASD warns that synchronised cloud storage can also be affected when files on a connected device are encrypted by ransomware. Cyber.gov.au
Keep your policy number and insurer’s contact details accessible alongside your records. Organise evidence by room and item identifier so you can find relevant documents without searching through unrelated files.
Update the inventory after major purchases, when items are sold or donated, and when you move home. Review it again at insurance renewal. RACV recommends annual inventory updates, including adding new belongings and removing those you no longer own. RACV
Start with one room today. List its contents, take the photographs and save a backup before moving to the next room.